Dark blue water surface background
Insurance Information

Water Damage Insurance Claims in Las Vegas: What to Know

We bill your insurance company directly and handle the documentation, so you can focus on your family.

Call 24/7: (702) 515-1485

We Make the Insurance Process Easier

Ultimate Choice Restoration works directly with your homeowners, condo, renters, or commercial insurance company on water, fire, mold, and sewage damage claims. We photograph the damage, record daily moisture readings, prepare a detailed scope of work, meet with your adjuster, and bill the insurance company directly. In a covered loss, you’re typically responsible only for your deductible.
  • Detailed photo and moisture documentation
  • Industry-standard estimating for adjusters
  • Direct billing to your insurance company
  • Help understanding what your policy covers
Call Now! (702) 515-1485
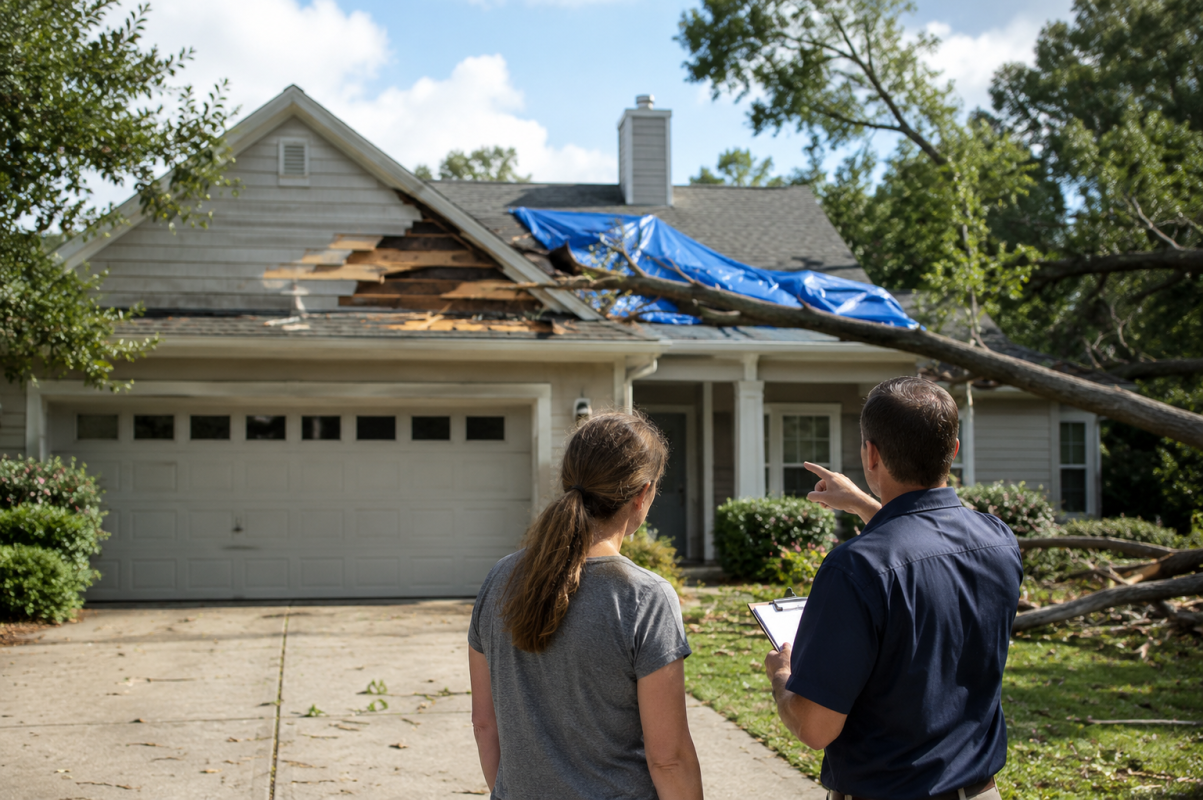
Homeowner speaking with an adjuster outside a storm-damaged house with a tarped roof

Tips for Filing a Water Damage Claim

  • Report the loss promptly – Most policies require timely notice and reasonable steps to prevent further damage.
  • Take photos and video – Capture damage before anything is moved or removed.
  • Start mitigation right away – Water extraction and drying are considered reasonable steps to limit the loss.
  • Keep receipts – Save receipts for emergency repairs, hotel stays, and meals if you are displaced.
  • Know your rights – You can choose your own restoration contractor.
Modern single-family home exterior with landscaped front yard

Types of Homeowners Insurance Policies

Understanding your policy form helps you know what to expect. Common policy types include:

  • HO-1 (Basic) – Limited named perils such as fire, lightning, theft, vandalism, and windstorm. Rare today.
  • HO-2 (Broad) – HO-1 perils plus others, including falling objects and certain sudden water discharges from plumbing and appliances.
  • HO-3 (Special) – The most common policy. Covers the dwelling against most perils unless excluded, and personal property against named perils.
  • HO-4 (Renters) – Covers a renter’s personal property and liability.
  • HO-5 (Comprehensive) – Broad open-perils coverage for both the dwelling and personal property.
  • HO-6 (Condo) – Covers a condo owner’s interior, improvements, and personal property.
  • HO-8 (Older Homes) – Designed for older homes, often paying actual cash value.

Most policies also include coverage for loss of use (additional living expenses if you can’t stay home), personal liability, and medical payments. Flood and mold coverage are often excluded or limited — flood insurance is purchased separately, and mold coverage may require an endorsement. Always check your specific policy or ask your agent.

This information is general and is not legal or insurance advice.

Dark blue water surface background

Questions About Your Claim? Call Us.

We’ll help you understand the process and start mitigation right away. Call (702) 515-1485 — a real person answers 24/7.

Call Now! (702) 515-1485 Request a Free Estimate